
Garrett Cahill
Growth at Nino
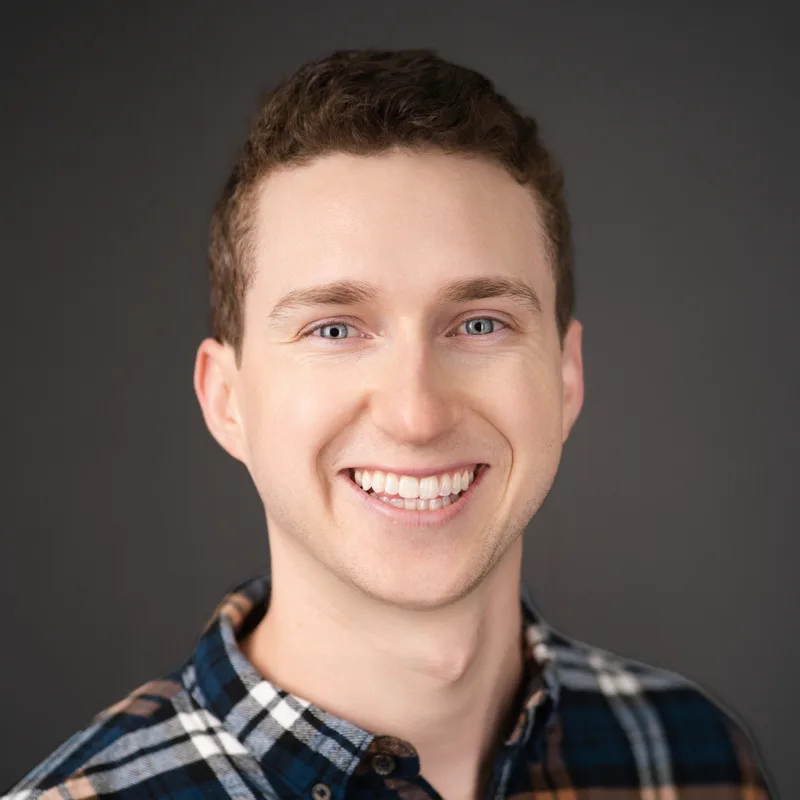
Garrett Cahill leads growth at Nino and writes its guides on tax and financial planning. A Nino CPA or financial planner reviews every article for accuracy.
First of its kind
Built the first cattle facial recognition model, in 2019.
YC W23
Founding member of Dealwise, an AI investment banking startup.
98
Nino articles written by Garrett.
What Garrett writes about
The topics of Garrett's Nino articles.
- Tax planning
- Financial advisors
- Equity compensation
- Personal finance software
- Retirement planning
- Financial advisor fees
- Flat-fee planning
- Restricted stock units
- Budgeting apps
- Capital gains tax
Written by Garrett
Best Fee-Only Financial Advisors in 2026: Hourly Planners and Planner Networks
Fee-only means paid only by clients. Find hourly and project planners through NAPFA, XY Planning Network, and Garrett Planning Network, and see where Nino fits for planning plus tax.
Are RSUs Taxed Twice? How RSU Taxes Actually Work
RSU vesting and a stock sale report different income. Learn how cost basis prevents double taxation and why withholding can still leave you with a tax bill.
How to Verify a Fiduciary Financial Advisor: Form ADV, BrokerCheck, and Questions to Ask
A fiduciary label on a website is not enough. Check Form ADV and Form CRS on IAPD, FINRA BrokerCheck, and the CFP Board lookup (see what a CFP is), then ask six questions in writing.
Financial Advice for Dual-Income Couples: A Year-Round Guide
Coordinate two incomes, employer benefits, withholding, and investment decisions with one household plan and a year-round planning calendar.
Flat-Fee Financial Advisor Cost: How It Compares to AUM
Compare a flat annual fee with AUM and hourly advice, calculate the break-even portfolio size, and check what the fee includes.
Choosing a Retirement Financial Advisor: What to Look For
A retirement financial advisor works out how much you need, adjusts your investments as the date nears, and turns savings into income. Here are the credentials to check, when hiring one pays off, and what it costs.
Retirement Planner vs. Financial Advisor: Which Do You Need?
A financial advisor covers your finances and investments across your life. A retirement planner turns savings into income, with taxes in mind. Neither title is regulated, so judge the credentials and the service list, not the label.
Should You Sell RSUs Immediately When They Vest?
Selling RSUs at vesting separates your pay from your next investment decision. Compare concentration risk, taxes, withholding, and a selling policy for future vests.
Do I Need a Financial Advisor for Retirement? When to DIY
No. Low-cost funds, the contribution limits, and a retirement calculator cover the saving years. The case for help grows at the transition, when Roth conversions, the Social Security claiming date, and withdrawal order are hard to undo.
Best Financial Planning Companies in 2026: Flat Fee, AUM, and Hybrid
Nino, Facet, Range, Domain Money, Vanguard, Betterment, Empower, Creative Planning, and Mercer Advisors compared on price in dollars, if tax filing is included, minimums, and who does the work.
Tax Planning for Retirement: Lower Your Lifetime Tax Bill
Tax planning for retirement manages your lifetime tax bill, not one return. Convert to Roth in the low-income years before Social Security and RMDs start at 73, then manage the thresholds each withdrawal can cross.
Donor-Advised Funds: How High Earners Cut Their Tax Bill
Since 2026, the first 0.5% of AGI you give buys no deduction and top-bracket deductions are capped near 35 cents. Here is how a donor-advised fund, bunching, and gifts of stock work around both.
LLC vs S Corp: When the S Corp Election Saves Tax
An LLC is a legal entity; S corp status is a tax election it can make. Here is what the election saves in 2026 once salary, the QBI deduction and payroll costs are counted.
Multi-State Taxes: Who Taxes You When You Move or Work Remotely
Moving doesn't end your old state's claim on the day the truck leaves. Residency tests, remote-work sourcing and equity that vests after you go decide which state taxes what.
Why Clients Outgrow AUM Advisors After a Liquidity Event
After a business sale or IPO the hard work moves to tax, estate, and structuring, while an AUM fee keeps rising with the balance. How to tell if your advisor kept up, and what fits instead.
What Happens to Your Stock Options and RSUs in an Acquisition?
The merger agreement decides whether your options and RSUs are converted, cashed out, accelerated, or canceled. Each outcome is taxed differently, and the closing year often costs more than payroll withholds.
Tender Offer Taxes: What Startup Employees Owe
Who buys your shares, which shares you sell, and how long you held them decide whether tender proceeds are taxed as wages or long-term gains, and how much of the bill arrives in April.
What Is an RSU? How Restricted Stock Units Work
A restricted stock unit is your employer's promise of shares once you vest. Here is how vesting works, why the vest is taxed as wages, and where RSU holders overpay.
How to Reduce Net Investment Income Tax
The 3.8% NIIT applies to the smaller of your net investment income or your MAGI over the threshold. Here is which lever to pull, and which popular moves only work on one side.
Mint alternatives (2026): what replaced Mint, and who pays for it
Mint shut down on March 23, 2024, and Intuit moved its users to Credit Karma, which has no Mint-style budgets and is paid by lenders when you take an offer. Here is how Credit Karma, Monarch Money, YNAB, Facet, and Nino compare when you want a budget, a planner, or financial planning and tax from one team.
Can You Change Your Taxes After Filing? How Amending Works
When to amend a tax return, how Form 1040-X works, and the deadlines and state-tax changes to check before you file.
Edward Jones alternatives (2026): a percentage of assets vs flat-fee planning and taxes
Edward Jones Advisory Solutions starts at 1.35% a year plus a 0.05% platform fee, and its advisors cannot give tax advice. Here is how Vanguard Personal Advisor Select, Facet, and Nino compare when you want financial planning, tax, or both.
Rocket Money alternatives (2026): bill cutting vs tax and financial planning
Rocket Money finds subscriptions and lowers bills, and from November 2, 2026, bill negotiation requires Premium+ at $15 a month. Here is how Rocket Money, Monarch Money, YNAB, Facet, and Nino compare when you want to cut bills, budget, or get financial planning and tax from one team.
Tax Strategies for High Income Earners, by Income Type
Which tax strategies are open to you depends on where your income comes from. Here are the levers for wages, a business, real estate, and investments, and which to plan a year ahead.
Capital Gains Tax When Selling Company Stock: What You'll Net
Federal capital gains tax, the 3.8% NIIT, state tax, and escrow each take a layer of a company stock sale. Here is how to estimate what reaches your account before you sign.
Do I Need a Financial Advisor? Start With Last Year's Tax Return
An index fund costs 0.03% a year, and advisors attribute most of a 1% fee to managing investments. The part of advice you can't buy cheaply shows up on your tax return. Here is how to read last year's return to decide whether you need a financial advisor, which kind, and what it should cost.
Pilot Alternatives (2026): Bookkeeping vs Tax + Financial Planning
The best Pilot alternatives depend on the job: Bench, Keeper Tax and Collective for company books and a business return, or Nino for financial planning and personal tax on a flat fee.
ISO Early Exercise for Founders: What the 83(b) Election Does and Doesn't Do
Early exercising ISOs can lock in a small AMT spread, but on ISO shares the 83(b) election does not start the capital gains clock. Here is how the rules work for founders, and when to skip it.
Vanguard Personal Advisor Alternatives (2026): When You Want Planning and Taxes on a Flat Fee
Vanguard Personal Advisor charges about 0.30% of enrolled assets once you want a human advisor. Here is how Digital Advisor, Schwab Intelligent Portfolios, Betterment, Wealthfront, Facet, Domain Money, and Nino compare when you want financial planning, tax, or both.
Pre-IPO Stock Option Tax Planning: The Founder's Checklist
A founder holds founder stock, ISOs, and NSOs at once, and the pre-IPO window closes several tax decisions on their own deadlines. Here is what to check, and in what order.
RSU Tax Planning: A Year-Round Strategy for High Earners
Project every vest for the year, model a few stock prices, and compare employer withholding to your household's tax before each vest, not in April.
RSU Vesting, New Job, Same Year: Model Your Tax Bracket
When RSUs vest at two employers in one year, each payroll withholds as if it were your only job. Here is how to size the gap and close it with W-4 withholding or estimated payments.
Concentrated Stock Position: How to Diversify Without Ignoring Taxes
Size the exposure, including shares still vesting, stress-test a drop, then sell down over several tax years under the 2026 capital gains and charitable rules.
Financial Advisor vs CPA: Do You Need Both?
A CPA files your return and can answer the IRS for you. A financial advisor plans what your money does next. Equity, a business or a sale usually needs both.
2026 Tax Changes: What to Do Before December 31
The One Big Beautiful Bill Act changed SALT, charitable, QSBS, and AMT rules for 2026. What changed, who it affects, and what to do by December 31.
Best AI Financial Advisors and Planners in 2026
Compare AI financial advisors and planners on price, data access, human help and taxes: ChatGPT, Origin, PortfolioPilot, Monarch, Range, Betterment and Nino.
CFP vs CPA: What's the Difference and Which Do You Need?
A CPA is a state-licensed accountant who handles your taxes. A CFP is a certified planner who advises on your whole financial plan. Here is when you need each.
Crypto CPA or Financial Advisor: Who Do You Need?
A crypto CPA handles cost basis, Form 8949, and 1099-DA reconciliation. A financial advisor handles allocation and concentration. When you need each.
How ESPP Is Taxed: Qualifying vs Disqualifying Dispositions
ESPP shares are taxed when you sell, and the holding period decides how much is ordinary income. See the math, Form 3922, and the 1099-B basis fix.
Facet vs Range vs Domain Money: Pricing, Tax Filing, and Who Each Fits (2026)
Facet, Range, and Domain Money compared on 2026 price, renewals, tax filing, who prepares the return, investment fees, and meeting access.
Tax and Financial Deadlines for 2026 and Early 2027: The Full Calendar
Every date from October 2026 to April 2027: estimated taxes, December 31 moves, tax forms, IRA and HSA deadlines, and the life-event clocks that run on their own.
How Much Can You Inherit Without Paying Taxes in 2026?
There is no federal inheritance tax, and estates under $15 million owe no federal estate tax in 2026. Five states tax heirs, and inherited IRAs are taxed.
How Much Does a CPA Cost to Do Your Taxes in 2026?
CPAs average $280 for a basic Form 1040 in NATP's 2025 study. See what schedules, states, K-1s, equity pay, and crypto add, and how EAs and software compare.
How Much of Your Paycheck Should You Save? A Guide for High Earners
The usual answer is 15% to 20% of pay. High earners usually need more, because Social Security replaces less of a large salary. Here is the order to save in.
SEP IRA: 2026 Contribution Limits, Rules, and Pros and Cons
A SEP IRA lets a business owner contribute up to 25% of pay, capped at $72,000 for 2026. Here is the self-employed math, the employee rule, and the deadlines.
Solo 401(k) vs SEP IRA: Which Saves More in 2026?
A Solo 401(k) beats a SEP IRA at most incomes because it adds a $24,500 employee deferral and catch-ups. See the 2026 math at $60K, $150K, and $300K.
What Is a CFP? Certified Financial Planner Requirements and Costs
What the CFP mark means, what it takes to earn it, how far the fiduciary duty reaches, what CFP professionals charge, and how to check one before you hire.
Where to Put Cash Above Your Emergency Fund: T-Bills, Money Markets, or Savings
Keep 3 to 6 months of spending in insured savings. Park cash you need within a few years in T-bills, money market funds, or CDs, and invest the rest.
Managing a Windfall: Withholding Is Not Your Tax Bill
How much of a windfall you keep depends on where it came from. Classify it, reserve for the tax, then pay down debt, hold cash, and invest the rest.
XY Planning Network Alternatives (2026): When You Want One Team for Planning and Taxes
XY Planning Network's fee-only advisors each set their own price and decide whether to file your return. Compare it with Garrett Planning Network, NAPFA, Facet, Domain Money, and Nino for planning and tax from one team.
Personal Capital Alternatives (2026): Beyond Net Worth Dashboards
Personal Capital is now the free Empower Personal Dashboard. Here is how to choose among Empower, Monarch Money, Origin, Facet, and Nino, depending on whether you want to track your net worth or get a plan and your taxes filed by one team.
TurboTax Alternatives (2026): When DIY Tax Software Is Not Enough
TurboTax is built to file your return: DIY, Expert Assist, or Full Service. Here is how H&R Block, TaxAct, Keeper Tax, Facet, and Nino compare, from seasonal software to an in-house CPA and Financial Planner.
Origin Alternatives: How to Choose When a Money App With Optional Financial Planner Sessions Is Your Starting Point
Origin lists a $99/yr membership with bookable financial planner sessions and DIY tax for eligible members. Compare it with Nino, Facet, and Domain Money when you want financial planning and tax with humans on one team.
Range Alternatives: How to Choose When a Flat-Fee Specialist Team Is Your Starting Point
Range lists Premium at $3,950/yr, Platinum at $5,950/yr, and Titanium at $12,500/yr, with personal tax filing on Titanium. Compare it with Nino, Facet, and Domain Money for planning and tax with humans on one team.
Best Flat-Fee Financial Advisors in 2026: Prices, Tax Filing and Fit Compared
Flat-fee financial advisors compared on price, tax filing and fit: Nino's CPA and Financial Planner team from $3,600 a year with filing, plus Facet, Domain Money and Range.
Financial Advisor With Tax Filing Included: Who Actually Prepares Your Return
Nino Advisor includes federal and state filing from $3,600 a year. Facet includes partner filing from Plus ($5,500 standard), Domain Money from Strategic ($5,200 in year 1), and Range only in Titanium ($12,500).
Garrett Planning Network Alternatives: How to Choose When Hourly, Advice-Only Planning Is Your Starting Point
Garrett Planning Network rates vary by member, with no income or account minimums for hourly engagements. Here is how it compares with Nino, Facet, and Domain Money for one-off advice or flat-fee planning and tax.
Keeper Tax Alternatives: How to Choose When Bookkeeping and Tax Filing Are Your Starting Point
Keeper Tax lists Monthly bookkeeping at $20/mo and annual plans from $199 to $1,199/yr with filing on Standard+. Here is how to choose among Keeper, Nino, Facet, and Domain Money when you need tax filing alone, or tax plus financial planning with a human team.
Kubera Alternatives: How to Choose When a Paid Net Worth Tracker for Crypto, Real Estate, and Alternatives Is Your Starting Point
Kubera Essentials is $250 a year and Kubera Black is $2,500 a year, after a 14-day trial with a $1 non-refundable fee. Here is how to choose among Kubera, Nino, Empower, and Monarch Money when you need a balance sheet alone, or financial planning and tax with a human team.
Morgan Stanley Alternatives: How to Choose When a Full-Service Financial Advisor or a Morgan Stanley Robo Is Your Starting Point
Morgan Stanley's Select UMA lists a maximum advisory fee of 2.0% a year; its Core Portfolios robo charges 0.30%. Compare Nino, Vanguard Personal Advisor, and Facet for advice without a percentage-of-assets wrap.
Quicken Alternatives: How to Choose When Desktop Money Management and Budgeting Software Are Your Starting Point
Quicken lists $6.99 to $12.49 a month, billed annually. Here is how it compares with Nino, Monarch Money, and Empower for tracking alone, or financial planning and tax with a human team.
YNAB Alternatives: How to Choose When Zero-Based Budgeting and Giving Every Dollar a Job Are Your Starting Point
YNAB is $14.99 a month or $109 a year, with a 34-day free trial and sharing for up to 6 people. Here is how to choose among YNAB, Nino, Monarch Money, and Empower when you need a budget alone, or financial planning and tax with a human team.
Betterment Alternatives: How to Choose When Automated Investing and Optional Premium Advice Are Your Starting Point
Betterment Digital is $5 a month or 0.25% a year (thresholds apply); Premium is 0.65% with advisor access (min $100k). Here is how to choose among Betterment, Nino, Wealthfront, and Empower when you need a robo alone, or financial planning and tax with a human team.
Empower Alternatives: How to Choose When a Free Dashboard and Optional AUM Advice Are Your Starting Point
Empower's Personal Dashboard is free; Personal Strategy advisory lists 0.89% AUM on common bands. Here is how to choose among Empower, Nino, Wealthfront, and Betterment when you need free tracking alone, or financial planning and tax with a human team.
Wealthfront Alternatives: How to Choose When Automated Investing and Cash Are Your Starting Point
Wealthfront is automated investing at 0.25% plus cash management. Here is how to choose among Wealthfront, Nino, Betterment, and Empower when you need a robo alone, or financial planning and tax with a human team.
Monarch Money Alternatives: How to Choose When Budgeting and Net Worth Tracking Are Your Starting Point
Monarch Money is paid budgeting and net worth software. Here is how to choose among Monarch, Nino, YNAB, and Empower when you need tracking alone, or financial planning and tax with a human team.
What Is Taxable Income? Definition and Example
Taxable income is income after eligible adjustments and deductions. See how it differs from gross income, AGI, and the tax you owe.
Roth IRA Contribution and Income Limits for 2026
The 2026 IRA contribution limit is $7,500, or $8,600 at age 50+. Income and contributions to other IRAs may reduce your Roth IRA allowance.
HSA Contribution Limits for 2026
The 2026 HSA limit is $4,400 for self-only coverage or $8,750 for family coverage. Eligibility, employer deposits, and Medicare can change your limit.
What Is Tax-Loss Harvesting?
Selling an investment at a loss can offset taxable gains. Learn the steps, see an example, and avoid wash-sale mistakes.
What Is the Net Investment Income Tax (NIIT)?
NIIT is a 3.8% tax on certain investment income above income thresholds. See who pays, what counts, and how to calculate it.
Mega Backdoor Roth 401(k): A Planning Guide for High Earners
Before you fund a mega backdoor Roth, answer three questions: how much to contribute, when to convert, and whether you have cash on hand for taxes.
401(k) Contribution Limits for 2026
The 2026 employee limit is $24,500. See age-based catch-ups, employer contribution limits, and the Roth catch-up rule.
Fee-Only vs. Fee-Based Financial Advisors: What Actually Changes?
Fee-only and fee-based describe how an advisor can be paid, not the quality of the plan. Compare compensation, conflicts, fiduciary duty, tax coordination, and total dollar cost.
How to Avoid an AMT Surprise When You Exercise ISOs
Exercising incentive stock options can create alternative minimum tax before you sell a share. Here is how to size the exercise so you keep enough cash and avoid a year-end surprise.
When Should You Exercise Stock Options?
Exercise stock options when the tax, cash cost, expiration risk, and company concentration fit one plan. This framework compares ISOs, NSOs, private-company risk, and holding periods.
Backdoor Roth IRA for High Income: A Year-End Planning Guide
A backdoor Roth stays open at any income. What decides the tax bill is the order of the two steps, the month they happen in, and what else sits in your IRAs.
What Is MAGI? How It Differs From AGI
Modified adjusted gross income starts with AGI, then changes for the tax or benefit being tested. Compare the Roth IRA, NIIT, Medicare, and Marketplace definitions.
Tax Strategies for High-Income W-2 Employees: The Levers Inside Your Paycheck
A W-2 earner can't deduct against wages. The tax levers are payroll forms: the W-4, 401(k) and mega backdoor elections, HSA and FSA picks, equity, and deferred comp.
What Does a CPA Plus a Financial Advisor Cost With RSUs?
Add the invoices, check which equity work is included, and assign ownership of withholding, sales, and tax filing.
A Tax and Cash Checklist for an Equity Liquidity Event
Before a tender offer, IPO-related sale, or acquisition, identify the taxable event, reserve cash, and reconcile your stock records.
RSU Tax Withholding: Why RSUs Look Taxed So High, and How Sell-to-Cover Works
RSUs are taxed like salary. Here is why a vest loses so many shares to withholding, why it can still leave you owing in April, and how sell-to-cover works.
Do Roth Conversions Count as Income?
The taxable part of a Roth conversion adds to ordinary income. See how basis, tax brackets, Medicare premiums, and other income tests affect the decision.
How Much Does a Crypto Tax Accountant Cost?
Crypto tax fees depend on record cleanup and return complexity. Compare software, reconciliation, filing, and representation as separate services.
Domain Money Alternatives: Compare Cost and Ongoing Support
Compare Nino, Facet, and Range with Domain Money, including first-year fees, renewals, required services, and software access.
Nino Is Live in Beta
A look back at Nino’s beta: accounts, equity scenarios, and financial questions in one place, with a human team to help.
Facet Alternatives: Compare Planning, Tax Filing, and Software
Compare Nino, Range, and Domain Money with Facet by required services, annual cost, tax-filing scope, and access to software.
ISO vs. NSO: Tax Differences and a Worked Example
ISOs can create AMT before a sale; NSOs usually create compensation income at exercise. Compare the cash cost and holding-period tradeoffs.
What Is a Trump Account? Eligibility and Contributions
Trump Accounts are retirement accounts for eligible children. Learn who can open one, how the $1,000 pilot contribution works, and what to check before funding.
529 Plan Changes: Education Uses and Roth Rollovers
529 plans offer more education uses and a limited Roth rollover option. Check account age, contribution limits, and state treatment before moving money.
From Stock Options to Spendable Cash: The Liquidity Math
An equity valuation is not spendable cash. Subtract exercise costs and taxes, then check when your shares can actually be sold.
Should You Sell Employer Stock When It Vests?
A useful sell-or-hold decision weighs tax reserves, company concentration, and cash needs. Here is how to compare them.
How Much Does a Financial Advisor Cost in 2026?
Financial advisor fees in 2026: about 1% of assets a year up to $1 million, a $4,500 median flat retainer, or $300 an hour. Compare models and what each costs.
What Is QSBS? Eligibility and Tax Exclusion Rules
Qualified small business stock may qualify for a federal gain exclusion. Acquisition date, company eligibility, holding period, and basis determine the benefit.
RSUs vs. Stock Options: Ownership, Risk, and Taxes
Compare how RSUs and stock options deliver value, when taxes arise, and what cash you need before choosing an action.
Buy, Borrow, Die: How It Works and What It Costs
Borrowing against appreciated assets can defer capital gains tax, but interest, collateral calls, and estate rules can outweigh the benefit.
How to File an 83(b) Election
An 83(b) election changes when restricted stock is taxed. Learn when it applies, how to file, and what to check within 30 days of the stock transfer.
Introducing Nino
Why we built Nino: AI software to understand your finances, with optional human help to plan your finances and taxes and put the plan into action.
Who checks Garrett’s articles
A Nino CPA or CFP professional reviewed each of Garrett’s 98 articles for accuracy.
Levi Larsen, CFP
Founding Financial Planner
Levi is a Certified Financial Planner with more than a decade of experience helping individuals and families plan their finances.
Reviewed 47 of Garrett’s 98 articles
Read Levi’s profileWarren Wu, CPA
Tax Lead
Warren brings over a decade of experience with complex individual and business tax returns.
Reviewed 26 of Garrett’s 98 articles
Read Warren’s profileShehan Chandrasekera, CPA
Head of Financial Services
Shehan leads tax strategy at CoinTracker and Nino and is a nationally recognized expert in cryptocurrency taxation.
Reviewed 21 of Garrett’s 98 articles
Read Shehan’s profile